Buying in the GTA
Buy with the numbers in front of you.
Know what you can afford, what it costs to close, and what to watch for, before you fall for a house.
Buying in the GTA
Know what you can afford, what it costs to close, and what to watch for, before you fall for a house.
Two calculators that share one set of numbers. Rates are pre-filled from today’s typical offers. Deciding between 5% and 20% down? Compare both paths.
Works the other way round: your income in, a realistic price range out, using the federal stress test lenders actually apply.
Enter the property once. You get the monthly payment, the land transfer tax, and the cash you need on closing day.
Estimates only, not a mortgage approval. Lenders differ, rates change daily, and your actual qualification depends on your full file. Land transfer tax shown uses the standard Ontario and Toronto brackets; homes over $3 million have higher Toronto tiers, so confirm those with your lawyer. Talk to a mortgage broker before making an offer.
What happens, in order. We walk you through each one.
Most buyers miss at least one of these. Several stack.
Current as of October 2026. Each program has conditions, so confirm yours with your lawyer and lender before you rely on it.
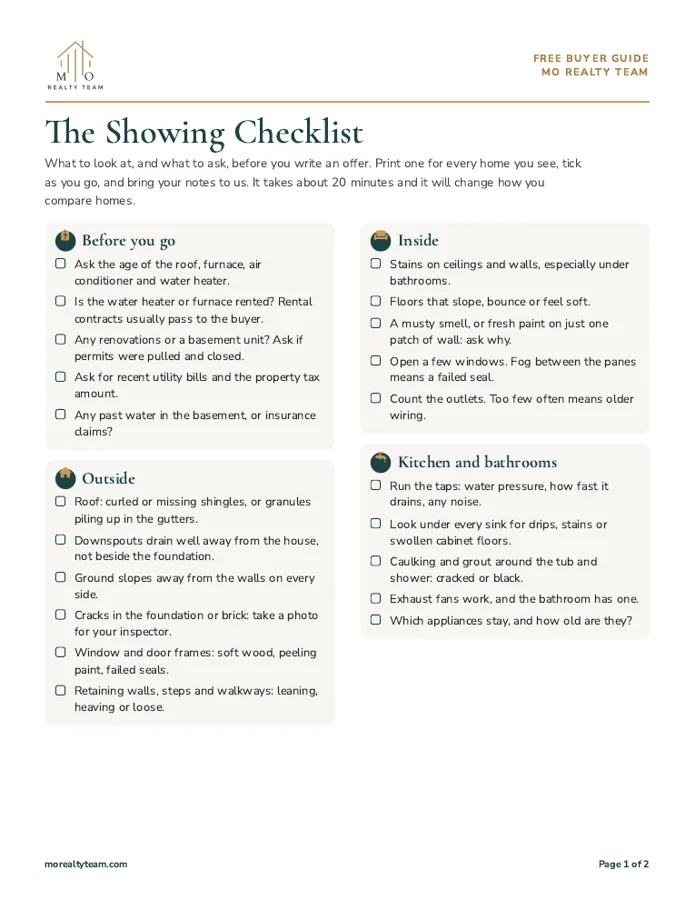
Free download
What to look at, and what to ask, before you write an offer. Two printable pages, built from years of showings and our own renovation and construction work.
Not a home inspection. Always book a licensed home inspector before you remove conditions.
Tap any one to open it.
Use the Home Buyers’ Plan for up to $60,000 each from your RRSP, an FHSA for up to $40,000 more, and the land transfer tax rebates on closing. Buying new? Ask about the HST relief and the first time buyer GST rebate too. A couple can each use the HBP and an FHSA.
A home inspection before you waive conditions. For a condo, have your lawyer read the status certificate: it shows the reserve fund and any special assessments. Arrange home insurance before closing; your lender will ask for it.
Freehold: you own the land and the building, no monthly fee, all the upkeep is yours. Condo: lower entry price and less upkeep, but a monthly fee. Check the reserve fund study and the board minutes.
Plan for 2 to 4% of the price on top of the down payment: land transfer tax, legal fees, title insurance, inspection and adjustments. The cost calculator above shows your exact figure.
Schools, transit, and what is planned nearby. We check development applications around any home you are serious about, because a tower two streets over can change your resale.
From the sold comparables, days on market and how motivated the seller is. We know when to offer firm and when to insist on conditions, including in bidding wars.
Search every active listing in the GTA, or book a call and we will build the plan with you.